Lam Research stock has been in a strong freefall this month. It dropped to $263, its lowest level since July 29, and 40% below its highest point this year. This sell-off may continue this week as jitters surrounding the artificial intelligence continues and as it publishes its financial results.
Lam Research earnings to show robust growth
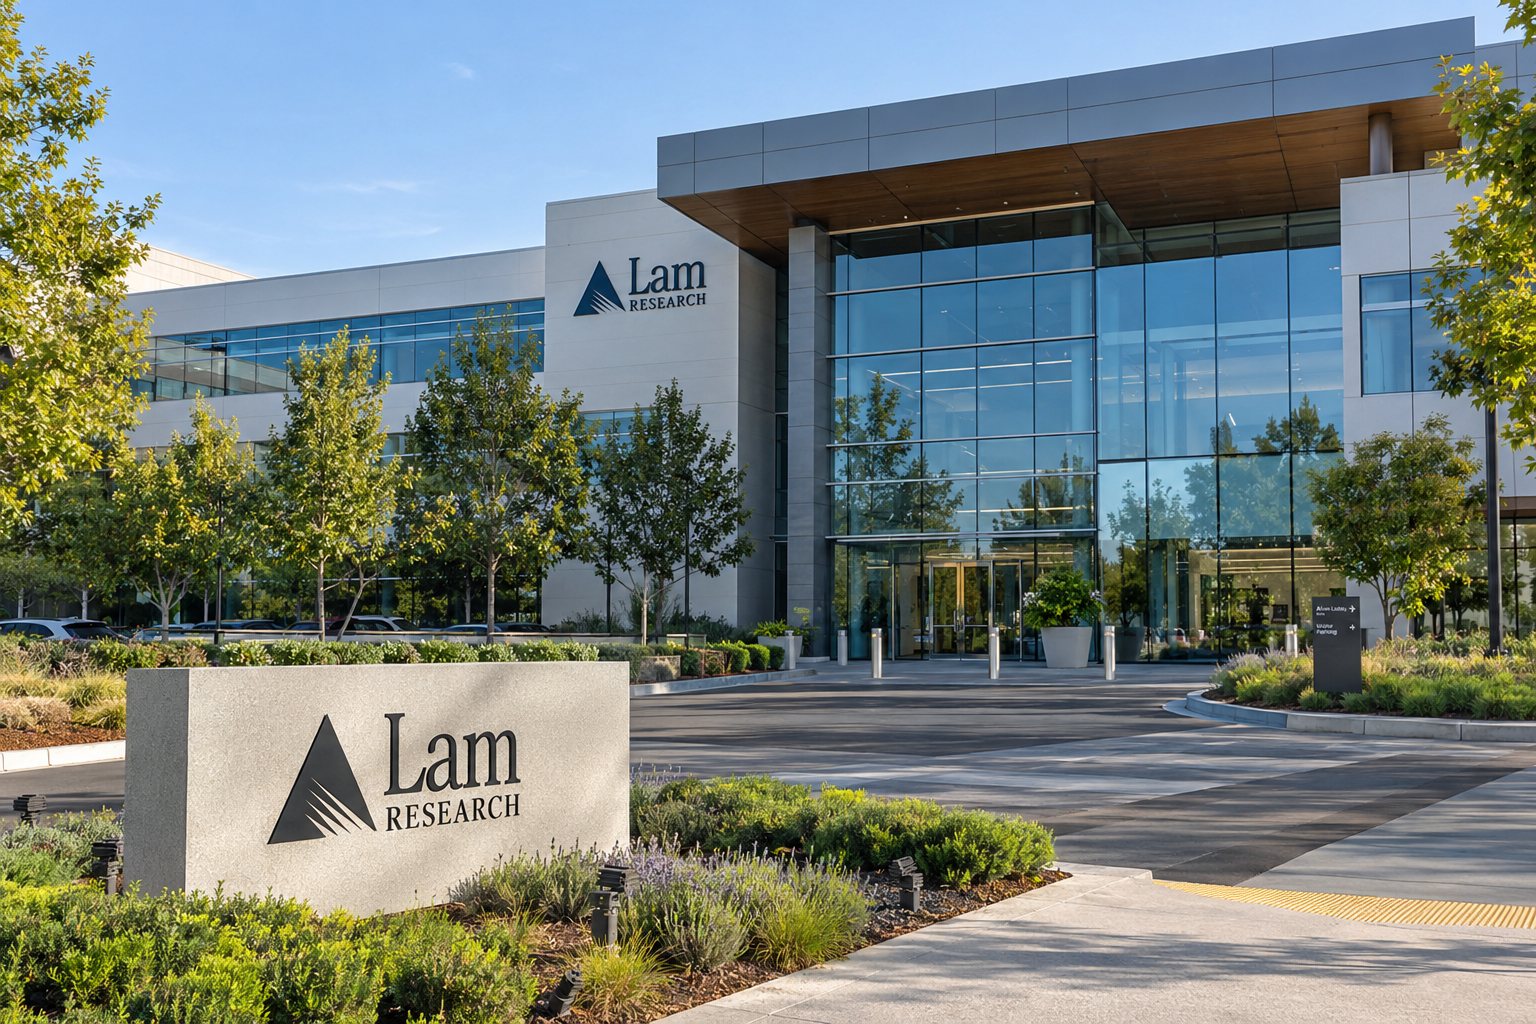
Lam Research is a top company in the semiconductor industry that manufactures equipment used in the chip-making industry. It focuses on areas like etching, deposition, cleaning and stripping, and advanced packaging.
Its technology is widely used in the making of DRAM, NAND, high-bandwidth memory and logic chips. As a result, it counts companies like Samsung Electronics, SK Hynix, Micron Technologies, and TSMC as its biggest customers.
As such, since these companies are seeing strong revenue growth, chances are that its revenue growth continued soaring in the third quarter. The most recent results showed that its revenue soared to $6.7 billion from $5.8 billion in the March quarter. Its gross margin continued rising, reaching 51.7%.
Most of its revenue was from Taiwan, followed by China, South Korea, and Japan. While it is an American company, the US revenue accounted for just 9% of its total sales, a notable thing since the US has a small market share in chip manufacturing.
Wall Street analysts are highly optimistic about the company’s growth. The average estimate is that its third-quarter revenue rose to $8.13 billion, up by 52% from the same period last year.
This growth will be followed by another 59% jump in Q4 to $8.52 billion. If this is correct, its annual growth rate will be 50% to $34.2 billion. Chances are high that Lam Research’s revenue will be higher than expected. Indeed, Morgan Stanley analysts predicted that the company’s guidance for the fourth quarter will be $9 billion.
Analysts are bullish on Lam Research, pointing to its strong revenue and profitability growth and its market share in the industry. Morgan Stanley recently hiked its target from $367 to $385, while Fundamental Research and B. Riley boosted it to $390. Berenberg analysts predict that the stock will hit $420, while UBS has a target of $425.
The general view is that its revenue and profits will justify its valuation, which has moderated a bit recently. Its forward price-to-earnings ratio stands at 27, slightly higher than the five-year average of 25.
Wyckoff Theory explains the ongoing Lam Research stock weakness
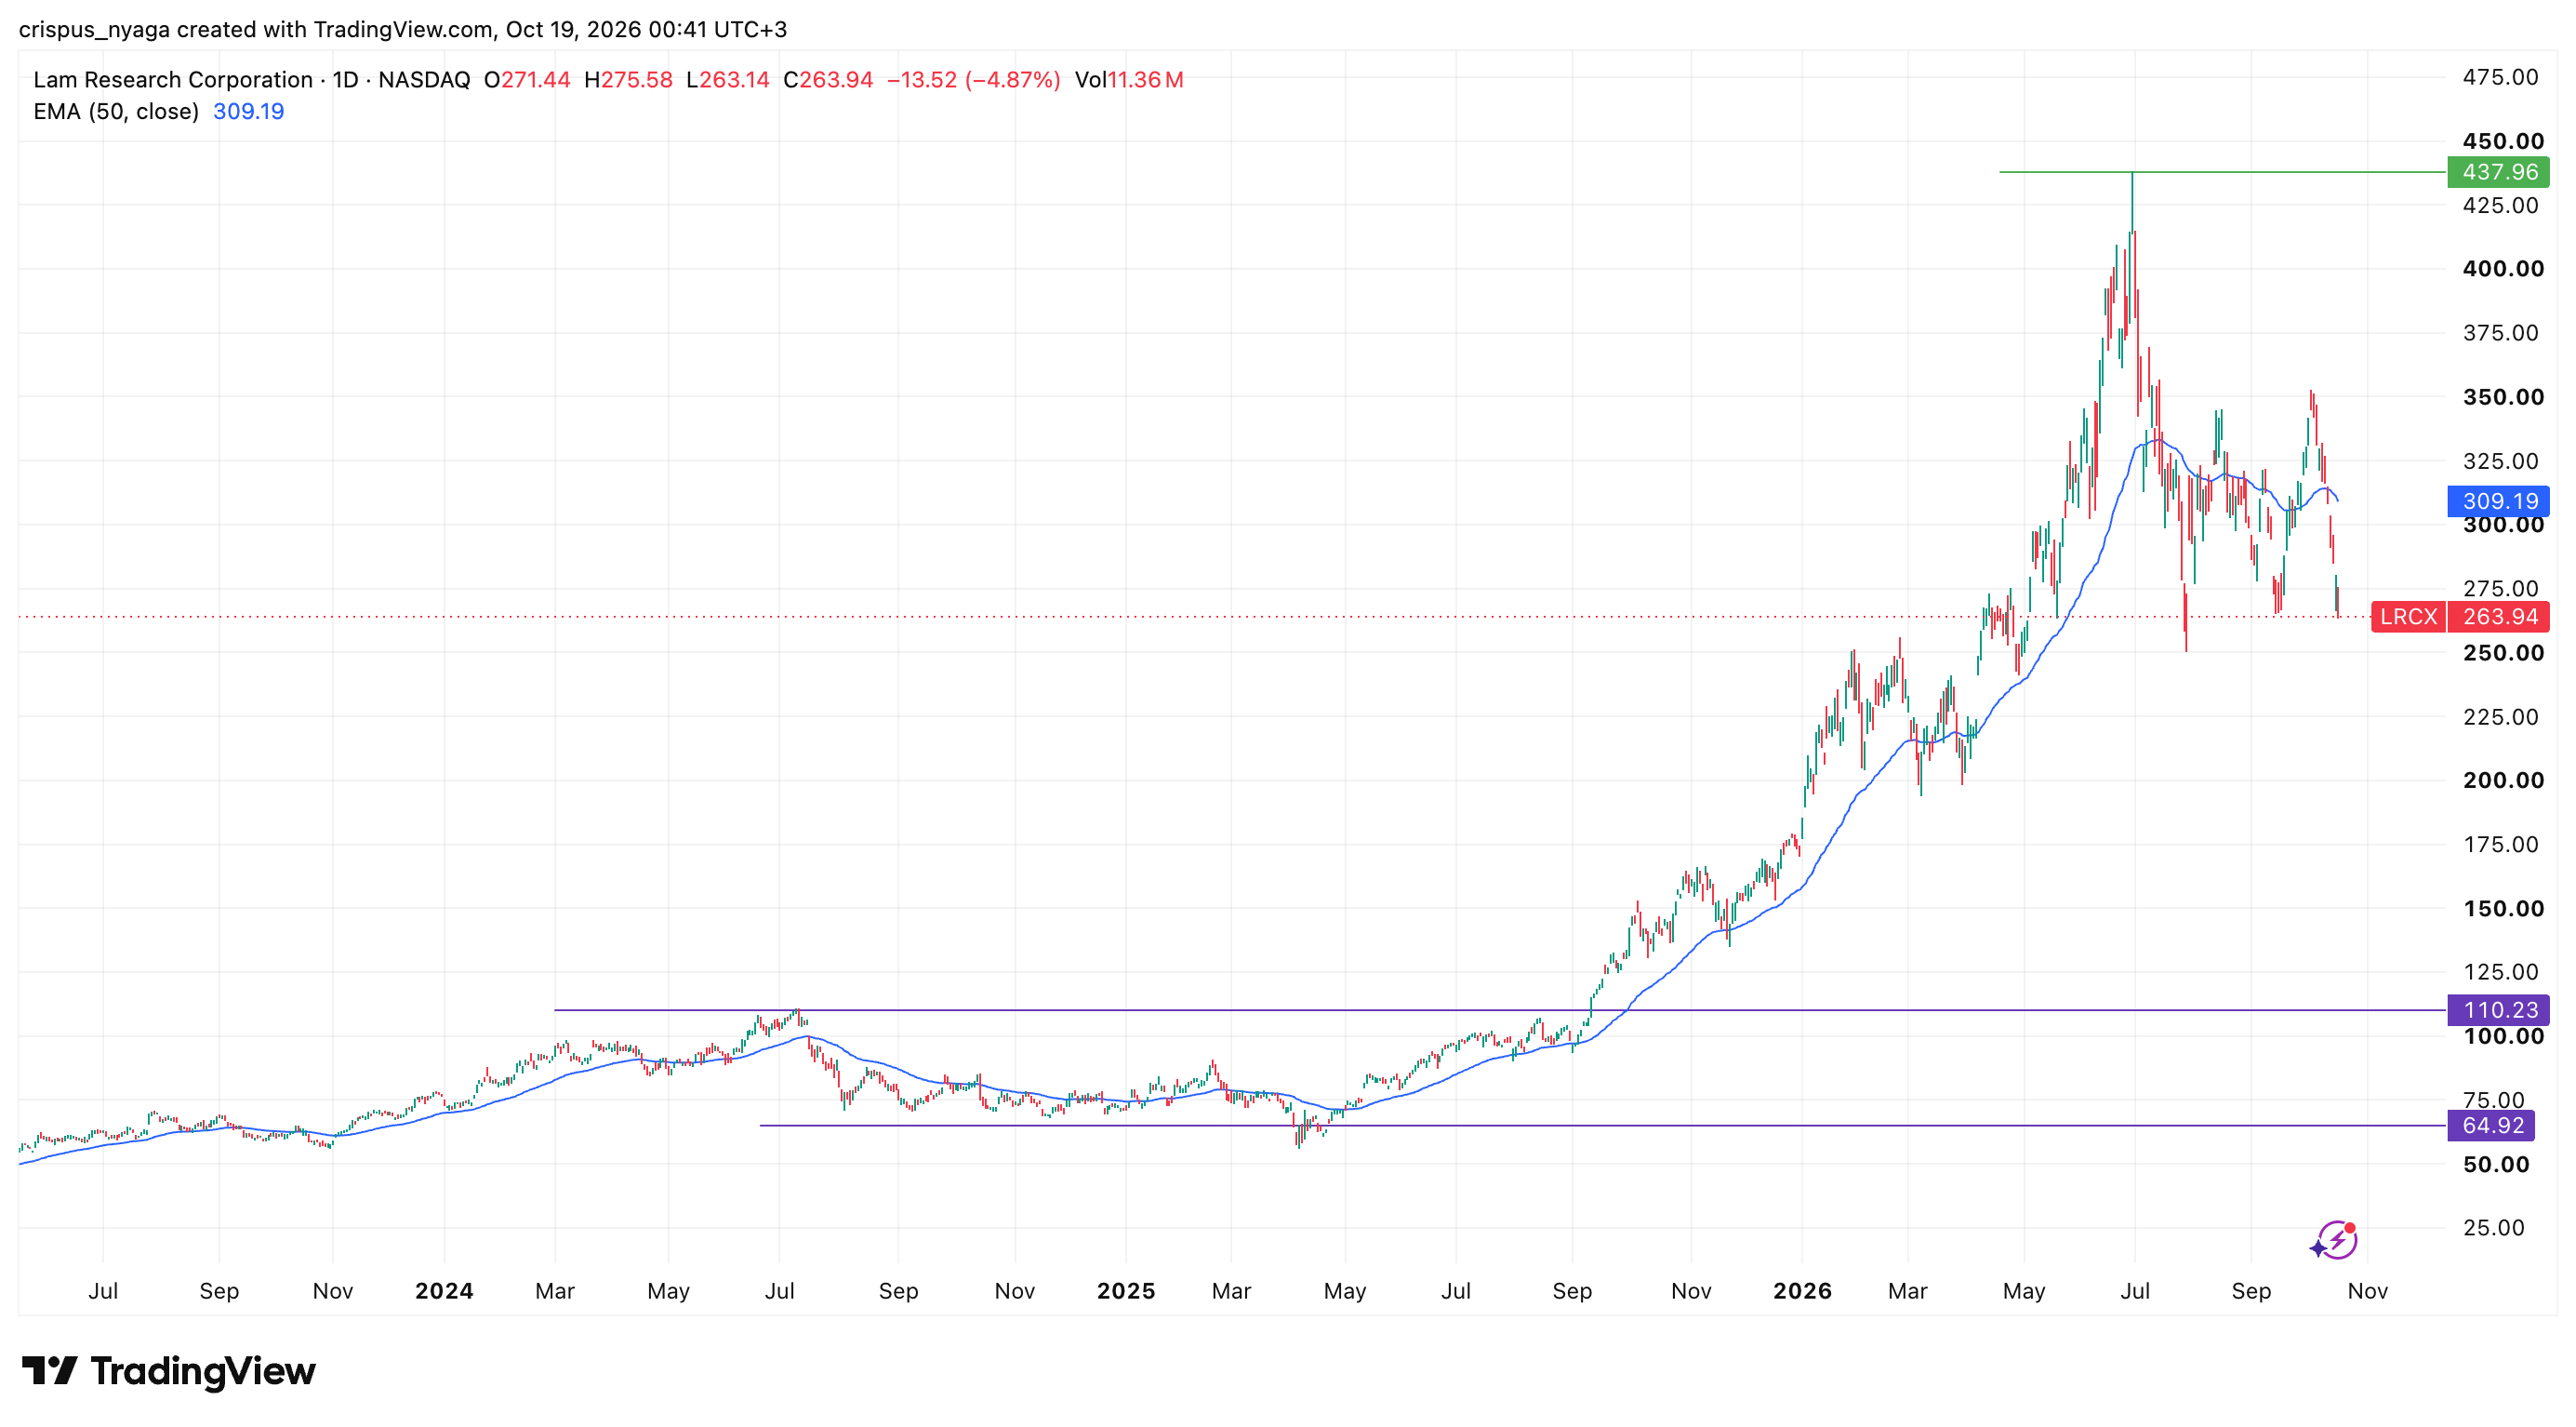
The daily chart shows that the LRCX stock remained in a narrow range for several years. This consolidation was part of the accumulation phase of the Wyckoff Theory. It then moved to the markup phase starting from early this year. This phase is usually characterized by higher demand from investors and speculators.
Now, there are signs that the stock has moved to the markdown and distribution phases. Therefore, there is a risk that Lam Research will continue falling, potentially to the psychological level of $200, down by 24% from the current level.